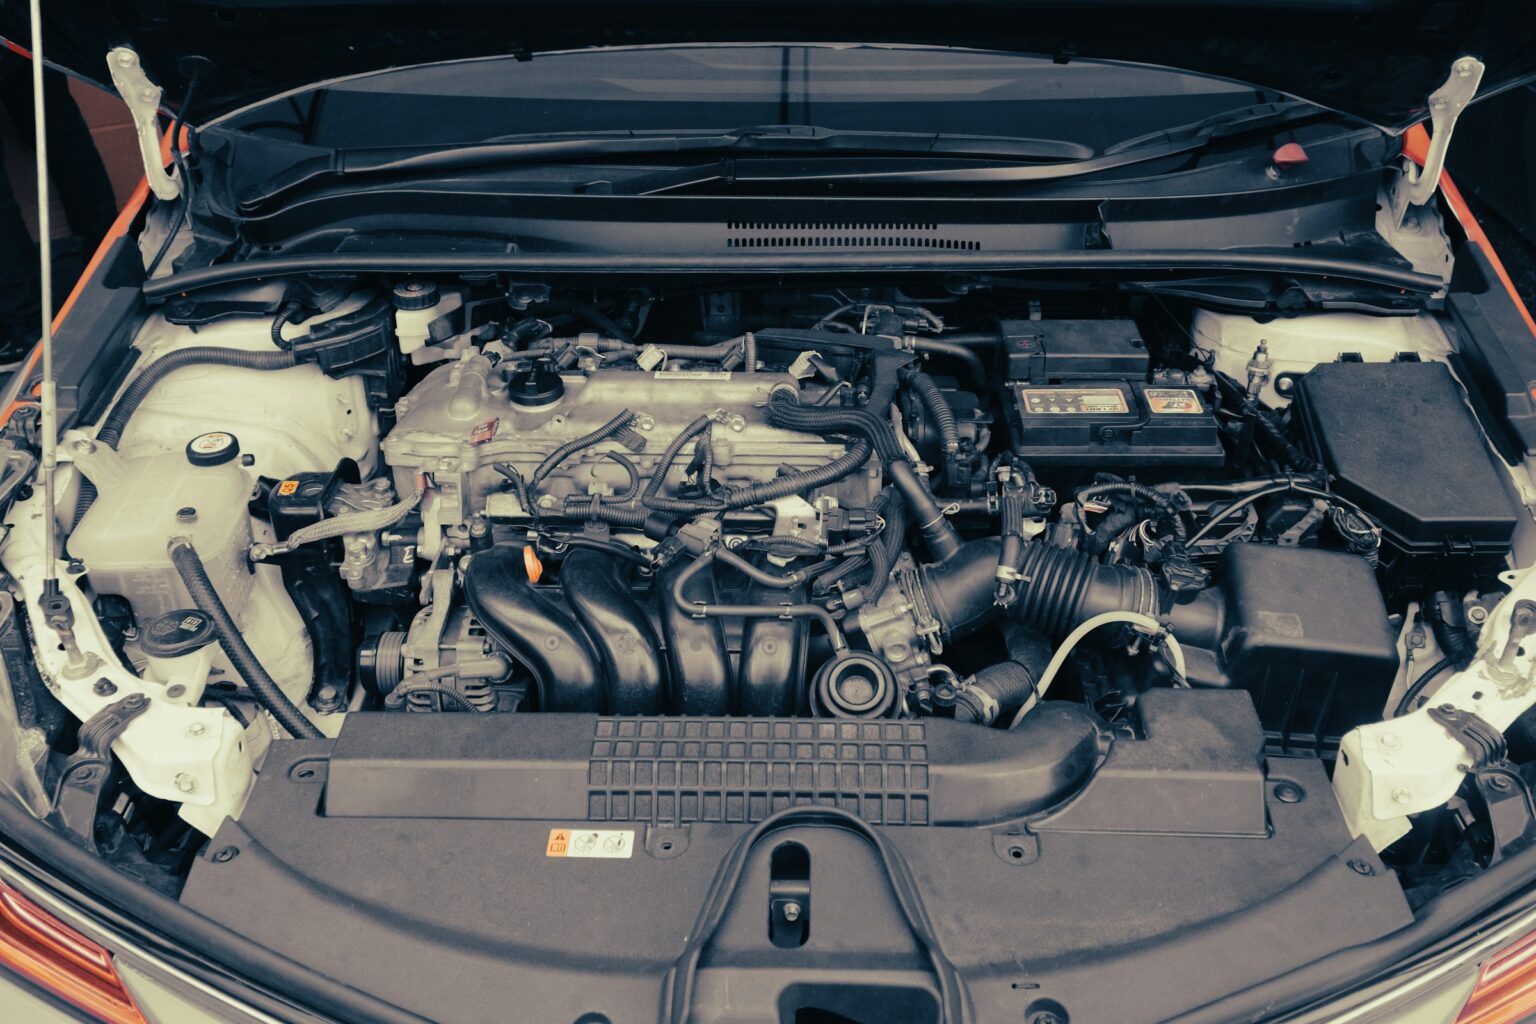
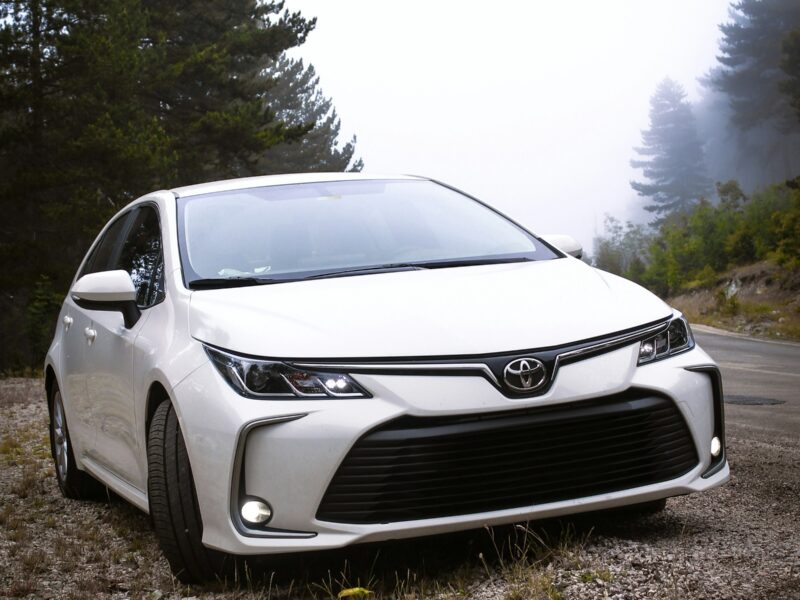
2020 Toyota Corolla
LE
*156 weekly payments at 24.9% APR with approved credit. Tax, title and fees extra.
1
Step 1 of 4
Four short questions, then a call or text from us with the down payment and the payment that fit your budget.
No Social Security number needed to start
About two minutes
Call or text us instead, if you prefer
2
Step 2 of 4
The amount you pay at the start. Tell us what you can comfortably put down and we work from there.
What you pay on each payday. We set it to your pay schedule, so it comes due when the money is there.
How many payments until the car is yours. We go over the full term with you before you sign anything.
Driverβs license
A current license or state ID.
Proof of income
Recent pay stubs, or benefit letters if that is how you are paid.
Proof of address
A utility bill or lease with your name on it.
References
A few names and numbers of people who know you.
Your down payment
Cash, a debit card or a trade-in toward it.
3
Step 3 of 4
25 cars in stock
Figures are examples for qualified buyers. Each car lists its own terms.
4
Step 4 of 4
Your payment comes due on the day you are paid β every week, every two weeks, twice a month or once a month. You choose how to pay it.
Online
From your phone, any time, through our payment page.
In person
At the store during opening hours, by cash or card.
By telephone
Call the store and pay by card over the phone.
Already a customer?
Make a paymentThe questions people ask us most, answered the way we would answer them across the desk.
More answersA past repossession or bankruptcy does not end the conversation. We look at where you are now: your income, how you are paid and what you can put down. Tell us about it when we call, and we will tell you plainly what we can do.
It depends on the car and on your budget, so there is no single number. Tell us what you can comfortably put down and we will show you the cars that fit it. Each car on this site lists its own down payment and terms.
Ask us, and we will tell you exactly what we look at before we look at anything. Most of what matters to us is not on a credit report: your income, your pay schedule and your down payment.
Call us before the due date if you can. We would rather work out a plan than add a problem. The contract you sign explains what happens when a payment is late, and we go through it with you before you sign.
Call the store first. Our service department looks at the car, and we go over what is covered before any work is done. The Buyers Guide on the window of each car says what the warranty covers.
Paying on time is the part you control. Ask us whether and where we report your payments.
Sample reviews. Replace them with your customersβ own words.
βNobody rushed me. They went through the payment and the term twice until I understood both, and nobody made me feel small for asking.β
DW
Dana
Arlington Β· drives a 2014 Honda Accord
βI asked a lot of questions. Every one got a straight answer, and the numbers on the website were the numbers on the paper.β
ML
Marcus
Lake Arden Β· drives a 2016 Nissan Rogue
βPaying every other Friday just works for me. I pay online in about a minute and I am done until the next one.β
TB
Teresa
Crestfield Β· drives a 2015 Chevrolet Malibu
Tell us about your car and we tell you what it can do toward your down payment.
Value my trade
Our service department works on the cars we sell. If something is wrong, call us first.
Request serviceA few short questions, then a call or text from someone at the store.
Pre-qualification is not an approval or a commitment to lend.